Indianapolis market brief · October 2026
What Is Actually Moving Indianapolis Real Estate Right Now
Rates are back over 7%. The metro has more listings. The luxury shelf still has its own clock. Here is the brief I would give a seller in Carmel and a buyer in Zionsville this week.
30-year fixed 7.03% Freddie Mac weekly average, week ending Sept. 24. First print above 7% since early 2025. | Indy active listings +20% Year over year in September. About 6,869 actives. National gain was closer to 5%. | Median list price $310k Down about 4% year over year. That is the metro list price. It is not your $2M brief. |
A buyer called this week because the rate printed over 7%. A seller in the same hour still wanted last spring’s number. Both of them were looking at Indianapolis. Neither of them was looking at the same market.
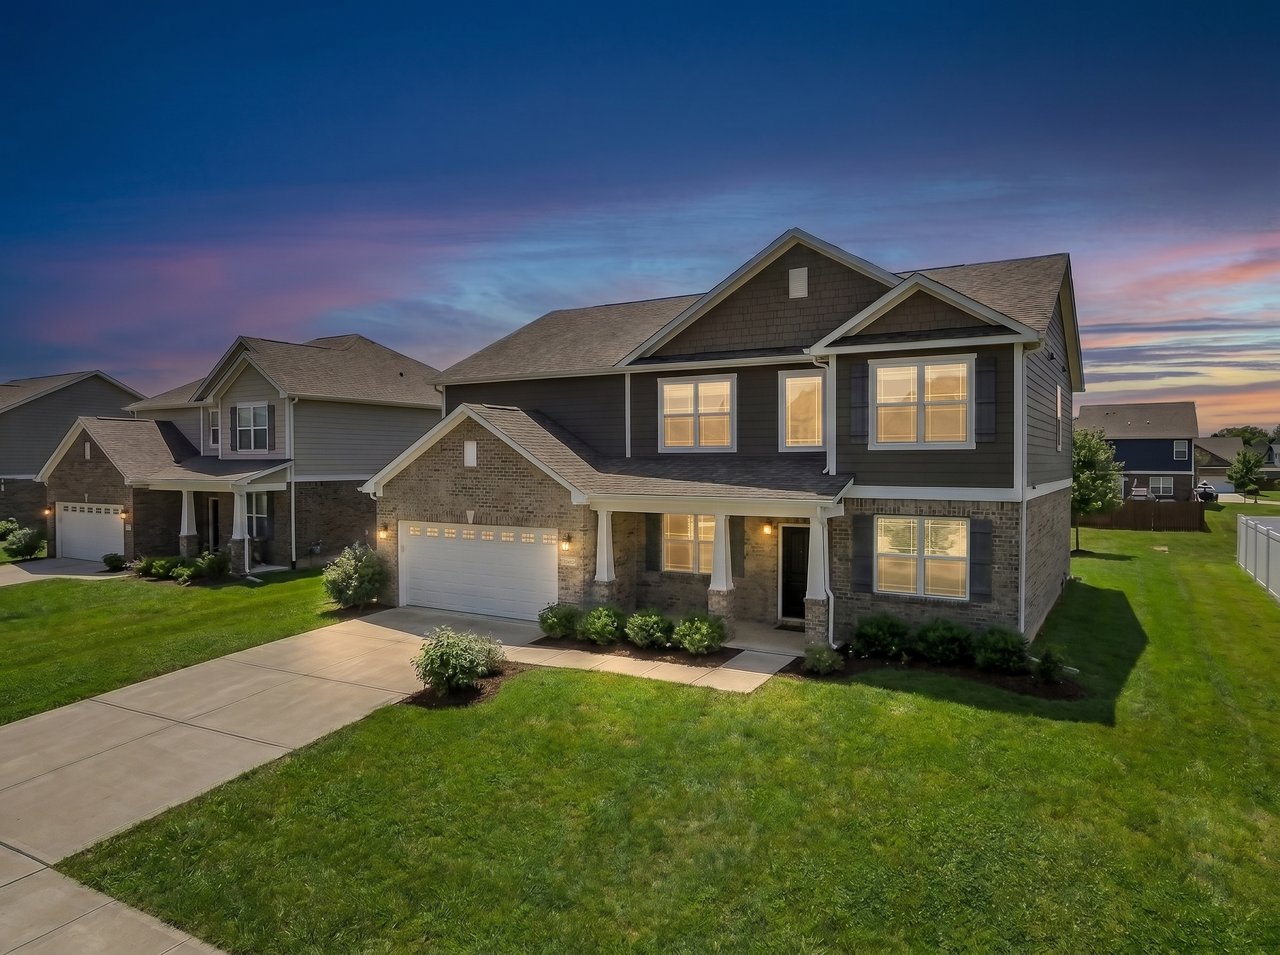
The metro got more inventory, more days on market, and more price cuts. Carmel, Zionsville, Geist, and Fishers did not turn into a distress sale. Luxury is a third clock on top of those two. If you read the September 30 buyer brief, this is the companion: what I would do with a listing, and what I would not let a headline do to the offer.
The rate is the story
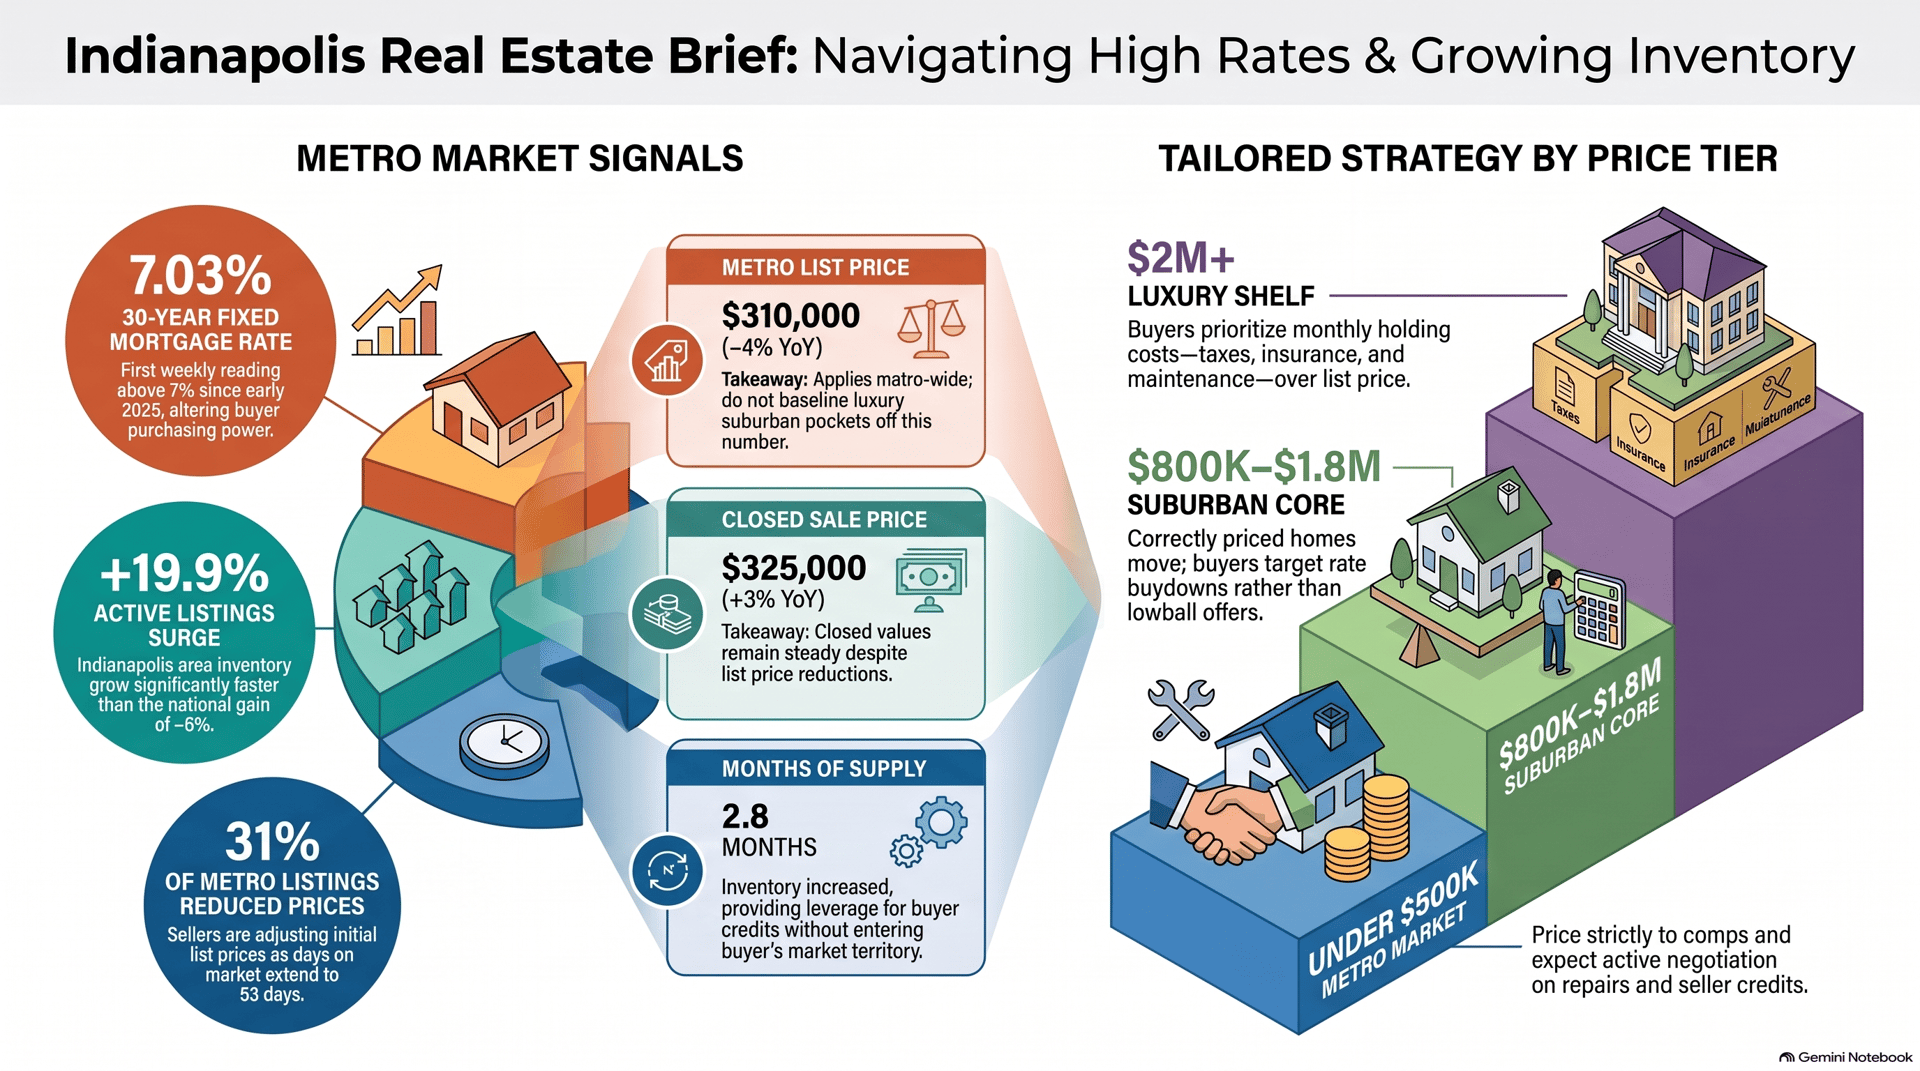
Freddie Mac’s weekly survey put the 30-year fixed at 7.03% for the week ending September 24, 2026. That was the first weekly reading above 7% since January 2025, up from 6.95% the week before and about 6.3% a year earlier. Some daily quotes later in the month ran higher.
On a mid-Carmel purchase, that move changes who can write. On a $2 million estate, the buyer is usually less payment-constrained and more freight-conscious: taxes, insurance, pool, and what January actually costs. Purchase price is the easy number. The monthly number is the listing.
I am not waiting for a rate miracle to do the work. The deals getting done are using credits, a buydown, or a cleaner inspection response. The ones sitting are still priced for a 6% spring.
Indianapolis got more choice. It did not get easy.
Realtor.com’s September snapshot had active listings in the Indianapolis area up about 19.9% year over year, to roughly 6,869. The median list price was $310,000, down about 4.1%. Days on market were about 53, up nearly 12% from a year earlier. Nationally, active listings were up closer to 5%.
Local closed-sale data is steadier than the list-price headline. Indiana REALTORS’ August report for the MIBOR-area market showed 2,859 closed sales, down about 6% year over year. The median sale price was $325,000, up about 3%. Active inventory averaged 7,544, up about 18%. Months of supply were 2.8, from 2.4 a year earlier. Median days to contract: 26, from 22.
Under three months of supply is not a buyer’s market in the textbook sense. It is a market with more room. Sale-to-list on homes priced to the comps was still near 98% in the July MIBOR read. More inventory is leverage on repairs and credits. It is not a license to treat every house as distressed.
Active listings, year-over-year change
Indianapolis added supply much faster than the country. The local closed-sale inventory count tells the same story with a different yardstick.
Price cuts are the national habit. Pricing is the local skill.
Nationally, 20.8% of listings took a price reduction in September, the highest September share since 2018, and the first month this year that cuts ran ahead of 2025. Realtor.com had Indianapolis price cuts on about 31% of listings in September, up slightly from a year earlier.
A reduction usually means the first number was a wish. It does not mean the street collapsed. Buyers read days on market before they read the kitchen. Two public cuts in three weeks is a story. One correct price is a strategy.
Signal | September read | How I use it |
|---|---|---|
U.S. price cuts | 20.8% of listings | Sellers are blinking. Do not inherit their first ask. |
Indy list price | $310,000, about −4% | Metro only. Do not negotiate Geist off this number. |
MIBOR sale price | $325,000, about +3% | Closed prices held. List prices got honest. |
Months of supply | 2.8 in the MIBOR area | More time. Not a clearance rack. |
Three clocks, not one market
Same city name. Different buyers. I would not make an offer, or a list price, off a blended median.
Band | What changed | What I would do |
|---|---|---|
Metro, under $500k | More listings, more time, softer list prices. | Price to the comps. Expect a real inspection conversation. |
$800k–$1.8M | This is where the year changed. A right price still moves. A wish takes longer. | Hunt terms, not a theatrical lowball. Credits and condition beat a headline discount. |
$2M and above | Small shelf. Fewer qualified buyers. Longer, quieter process. | Underwrite taxes, insurance, pool, and land before anyone talks price. |
On my September 30 pull there were 39 active listings at $1 million and up on the Central Indiana shelf I work. Refresh that count the morning you publish. A house at $2.6 million is competing inside that list, not against a $325,000 closed sale on the other side of the county.
New construction is competing on the monthly
New-home applications in the Indianapolis area rose for a third straight month into August, with Hamilton County leading several of the county gains. Nationally, new homes have been selling for less per square foot than resale in a large share of major markets, and builders are using incentives because they are carrying months of supply the resale market is not.
If you are selling a resale in Carmel or Zionsville, the comp set now includes the spec house with a rate buydown. Presentation, lot, and condition have to earn the premium. If you are buying, ask what the incentive is worth in payment, not just what the brochure says the house is worth.
What I am actually negotiating
- Credits and buydowns instead of waived inspections.
- A second look instead of a same-day offer. Urgency you do not feel is expensive.
- Off-market when the public shelf at the top is thin. The best Geist and Zionsville houses are not always on a portal first.
- A written buyer agreement before the first tour. The listing agent already has a client. That is the job on your side of the table.
If you are selling this fall
01 | Price off the last 90 days in your band. Not last spring. Not the metro median. |
02 | Stage and photograph for the second visit. The first visit is no longer automatic. |
03 | Decide the concession before the buyer asks. Rate credit, closing cost, or a clean inspection response. |
04 | Do not chase the market down in public $25,000 steps. One correction beats three stories. |
05 | If the house is land, water, or privacy, market it as that. It is not competing with a $325,000 sale. |
If you are buying, or selling here and buying on the Gulf
Start with the band, not the city slogan. Carmel Clay schools, a Geist dock, a Zionsville lot, and a Sarasota condo are four searches. I can run the Indiana side and the Gulf side in the same relationship. I will not pretend they price the same way.
If you are still in another state, we build the short list and video the houses that survive the memo. You do not burn a trip on inventory that fails the math.
The only move that matters this week
Tell me the band. I will tell you if the market has the house.
Selling in Carmel, Zionsville, Geist, or Fishers: start with a valuation, not a guess from last spring. Buying: representation before the first tour. Relocating to Sarasota in the same year: one advocate, two licenses.
Call or text (317) 999-9888 · Home valuation · Buyer’s agent · Sarasota
Figures are directional and vary by source and price band. 30-year rate: Freddie Mac Primary Mortgage Market Survey, week ending September 24, 2026. Indianapolis list price, active listings, days on market, and price-cut share: Realtor.com local snapshots, August–September 2026. MIBOR-area closed sales, median sale price, inventory, and months of supply: Indiana REALTORS, August 2026. National price-cut share: Realtor.com, September 2026. The $1 million-plus count is Cara Conde’s MLS pull and should be refreshed on the publish date. This is not a commitment to lend, and it is not an offer to sell a specific property. Verify against a current pull before you write.
Cara Conde · Realtor®, Broker · Certified Negotiation Expert · Certified Luxury Home Marketing Specialist · Indiana #RB18001820 · Florida #SL3665708 · caraconde.com